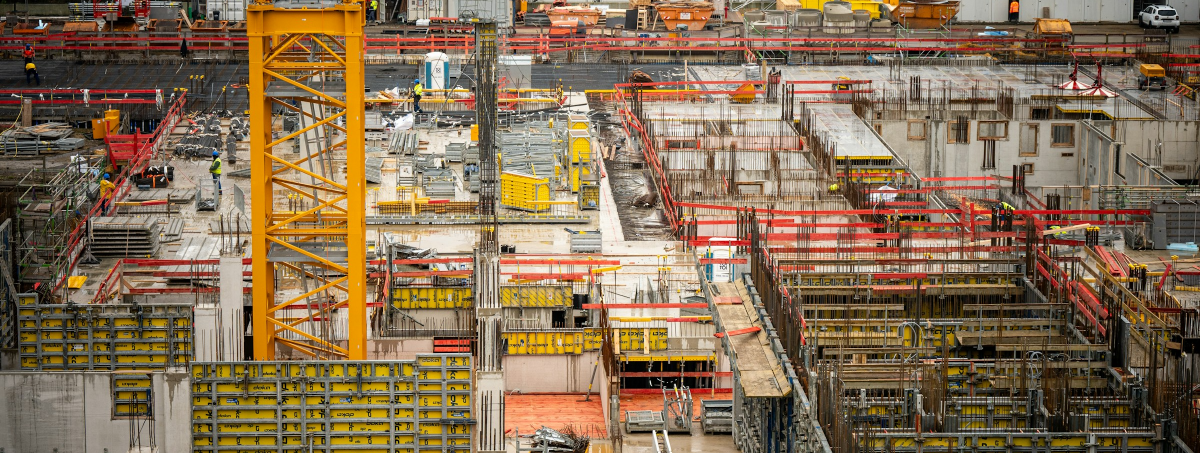
The UK construction industry is drawing closer to recovery with each passing month. The S&P Global UK Construction PMI for September 2026, published on 6 October, rose to 46.1 from 44.3 in August, the strongest performance for eight months and significantly ahead of the 44.9 reading expected by economists. While the sector has been contracting every month since January 2025, the direction of travel is clearly improving, and construction leaders on both sides of the Irish border should read September’s data with measured confidence.
The S&P Global findings are a compelling forward signal. All three construction sub-sectors showed a degree of stabilisation relative to the rapid declines recorded in the second quarter of 2026. Three dimensions define the improving picture: a civil engineering segment regaining momentum, a commercial sector approaching its best performance since mid-2025, and a shift in market activity toward infrastructure-led sectors where investment pipelines remain genuinely strong.
The sub-sector detail is instructive. Commercial building recorded its smallest fall since May 2025, while civil engineering improved across transport, energy and data centre construction. Tim Moore, economics director at S&P Global Market Intelligence, noted that all three construction sub-sectors have seen a degree of stabilisation relative to the rapid declines of the second quarter. Housebuilding remained the weakest performer, as rising borrowing costs and unfavourable market conditions weighed on output, but even here the rate of decline moderated.
Carly Thorpe, construction and engineering partner at Walker Morris, identified the broader structural signal with clarity. The September figures reinforce what practitioners across the construction sector have been observing: market activity is shifting decisively toward infrastructure-led sectors including transport, energy and data centres, where investment and project pipelines remain stronger. In Ireland, where the AIB Construction PMI held positive at 50.7 in August and commercial construction led the sector, the same infrastructure-first dynamic is generating sustained demand.
The cost and employment picture still requires active management. Around 25% of construction companies surveyed reported a rise in purchasing costs in September, with fuel surcharges, higher freight and rising raw material prices all noted. New orders remained subdued as clients deferred decisions linked to geopolitical uncertainty, and employment fell for the ninth consecutive month. Construction leaders should build price escalation provisions into pipeline contracts and maintain workforce investment in readiness for the recovery this improving PMI trajectory now clearly signals.
The UK construction industry has endured its longest sustained contraction since the financial crisis era with resilience and resolve. September’s PMI of 46.1 is not yet recovery, but it is its clearest precursor to date. Organisations that manage cost risk with discipline, sustain their people and position decisively for the infrastructure-led pipeline ahead will be best placed to lead when the recovery completes.
.png)